

Spirits and cider sales stayed broadly stable in the two-week period ending October 18, while trends for flavored malt beverages (FMB) and seltzer worsened, according to analysis of NIQ data from Goldman Sachs Equity Research.
NIQ uses US x AOC (extended All Outlet Combined) including convenience stores to summarize multi-channel markets and aggregate all national cross-outlet market data, and includes certain retailers (such as Whole Foods Market) that other providers do not.
Overall, total alcohol beverage dollar sales declined -5% in the two-week period (-4.5% 4W). Volume trends dipped -3.9% (-3.4% 4W) against slight pricing declines (-0.1% 2W and 4W).
Category Highlights
- RTDs: Spirits-based RTDs continue to carry the category (+25.6% 2W/ +27.2% 4W), while wine-based RTDs are growing even faster (+29.6% 2W/ +29.1% 4W).
- Cider: Cider was another positive, as sales rose 3.4% in the two-week period (+3.9% 4W), with volume up as well (3.7%).
- Spirits: Spirits were down (-3.7% 2W/ -3.2% 4W). Volumes rose 2.4%, likely thanks to RTDs, though average prices declined -5.9%.
- FMBs: Continuing to slow against stronger RTD pockets, sales dipped 8.7% in the two-week period (-7.7% 4W). Twisted Tea declined -13.3% but saw share expansion, while Simply Spiked was down -37.2% (-32.3% 4W).
- Hard Seltzer: Nothing new bubbling up here – sales were down 6.9% (-6% 4W), with leader Truly falling 15.7% and share continuing to contract.
- Beer: Dollar sales fell 5.1% in the latest two weeks (-4.4% 4W), driven by -6.2% volume declines, partially offset by +1.1% pricing.
- Wine: In line with beer, sales dipped 5.6% (-5.7% 4W), with volumes down 5.9%.
RTDs Drive Wine, Spirits Growth
With double-digit growth and minimal pricing pressure, spirits and wine-based RTDs are reinforcing that RTDs remain the clearest bright spot in retail. But some major names are beginning to lag.
High Noon remains the category leader (18.4% of spirit-based RTD absolute dollar share) but saw sales dips (-7.8% 2W/ -6.1% 4W) and velocity slow (-14.9% 2W/ -13.7% 4W). Distribution and pricing is roughly steady.
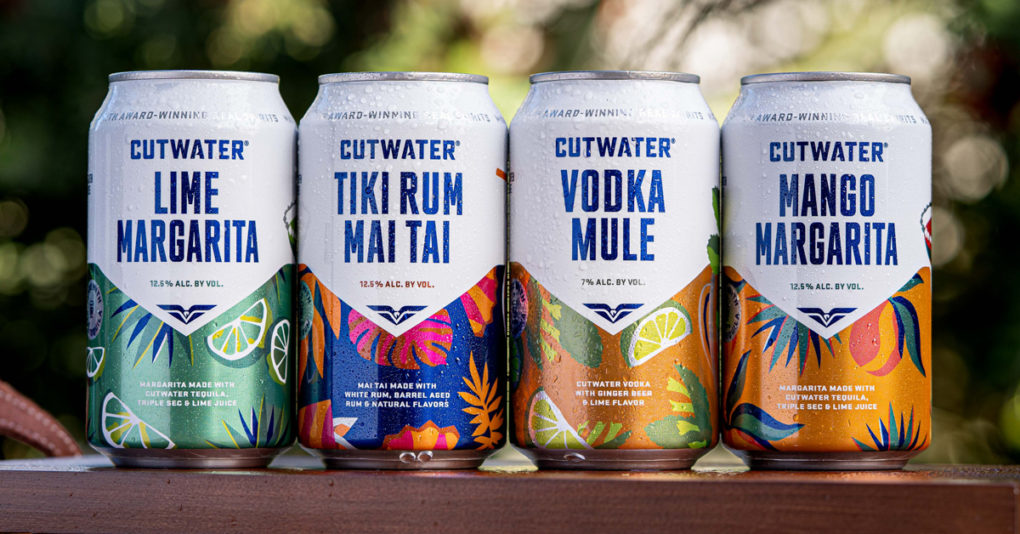
Cutwater, on the other hand, is continuing to expand in dollar sales (+135% 2W/ +135.8% 4W) and distribution. Nutrl saw positive but moderate growth (+17.0% 2W/ +16.5% 4W).
As for major brand extensions, Jose Cuervo sales continued to decline (-8.8% 2W/ -9.1% 4W) and Jack Daniel’s RTD sales are soft (-13.7% 2W / -13.4% 4W) with continued negative velocity (-14.3%).
Meanwhile White Claw Spirits Cocktails and Truly Cocktail reported a sales drop of -89.9% and -94.6%, respectively, in the two-weeks.
Sales of Fresca Mixed Cocktail continued to decline at -27.3%, a stat that the executives at The Coca-Cola company are likely hoping could see some change as the brand transitions to Sazerac’s portfolio from Constellation Brands.
In the battle for the spiked tea crown, sales for Surfside and Boston Beer’s Sun Cruiser remain strong on a 52-week basis and in recent windows (Surfside: +98.7% 2W / Sun Cruiser +280.3% 2W). Surfside’s distribution (43% ACV) and dollar share (7.2%) remain sizable while Sun Cruiser continues to post those large sales gains.
In wine RTDs, BuzzBallz and BeatBox remain the top dollar share drivers. BuzzBallz is up in sales (+70% 2W/ +68.4% 4W), while BeatBox sales were steady (+24.6% 2W/ +25% 4W). Smaller wine-based RTD companies (Daily’s, Rancho La Gloria) were down by single-digits in sales, while Big Sipz remained steady (+23% 2W/ +23.7% 4W).